

In our last natural gas article, published on Oct 27, we noted that market participants became overly bearish too early. We wrote:
The bearish weather demand isn’t translating into outlandish storage injections, though I would caveat that we are likely to see storage injections into mid-November if the weather doesn’t turn colder soon.
But for the most part, I think the market has already priced in the bearish injections. In order for December Henry Hub contracts to fall to where November is trading at today ($3.035 down to $2.616), you would need materially bearish weather to persist in the 2nd half of November, and I don’t know if that will be the case.
These forecasts will change materially over the coming weeks, but right now I see signs of colder risk at the end of November. If market positioning remains so one-sided, we could see a potential short squeeze by the 2nd week of November (when the forecast will start to show the end of November).
Natural gas has surged recently thanks to colder weather forecasts through the end of November, but does it have more room to rally?
What’s going on?
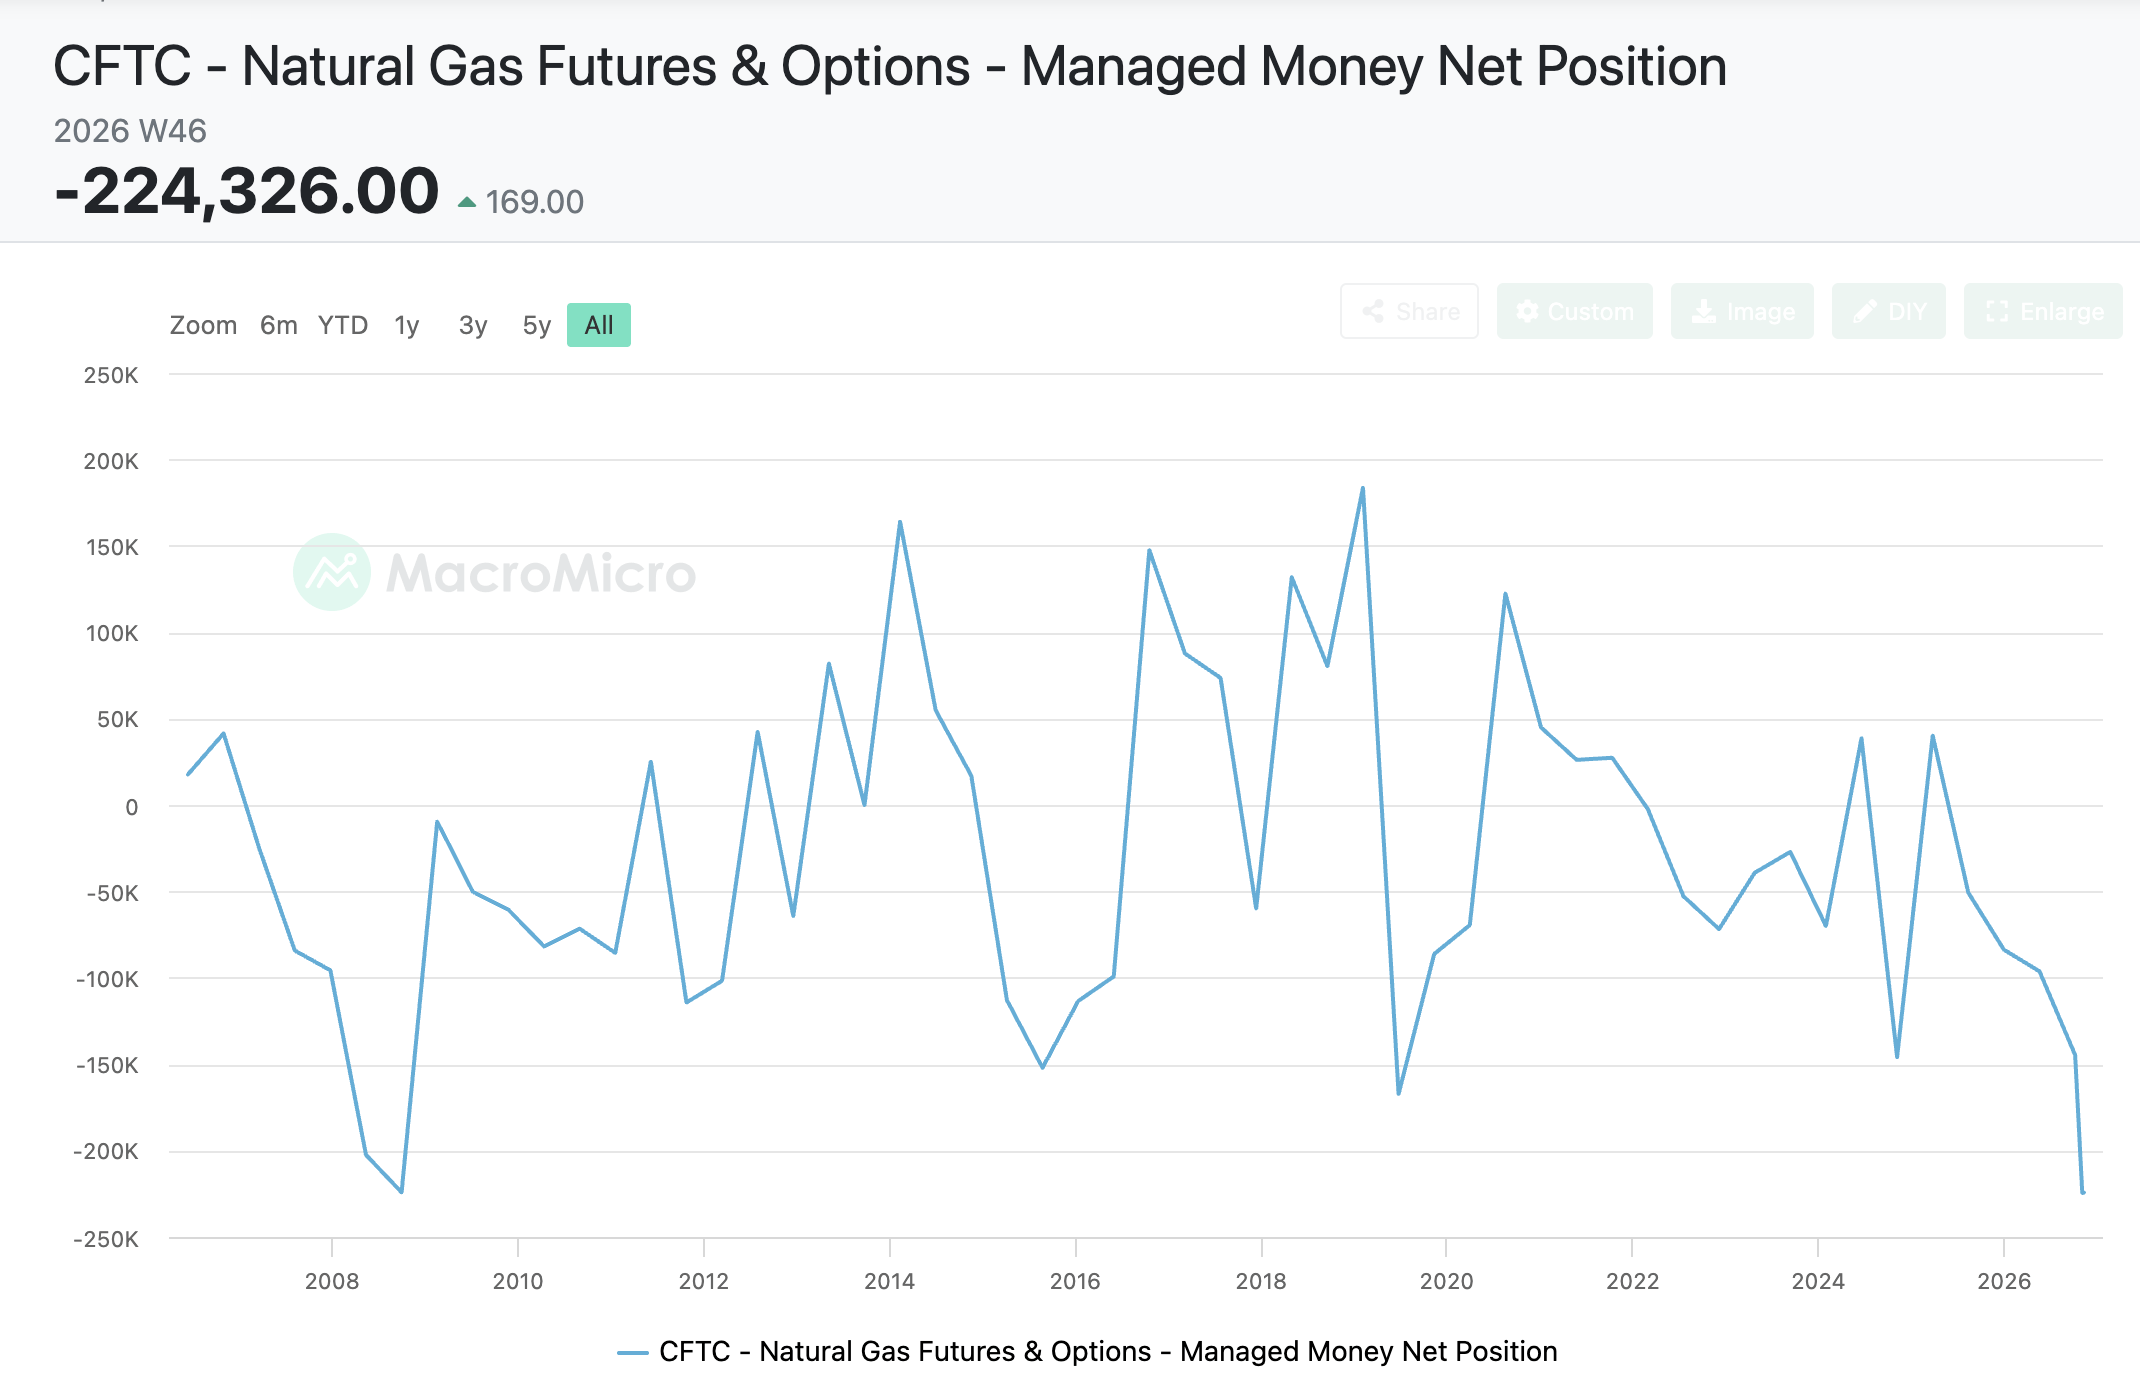
Speculator positioning got too one-sided by the time of our last update. Money manager positioning reached an all-time high on the short side.
Source: MicroMacro
On a net basis, positioning remains terribly one-sided, which will likely lead to frequent short-squeeze events throughout the winter gas trading session.
Following the latest short squeeze, positioning won’t be as extreme, but market participants will remain bearish.
Why?
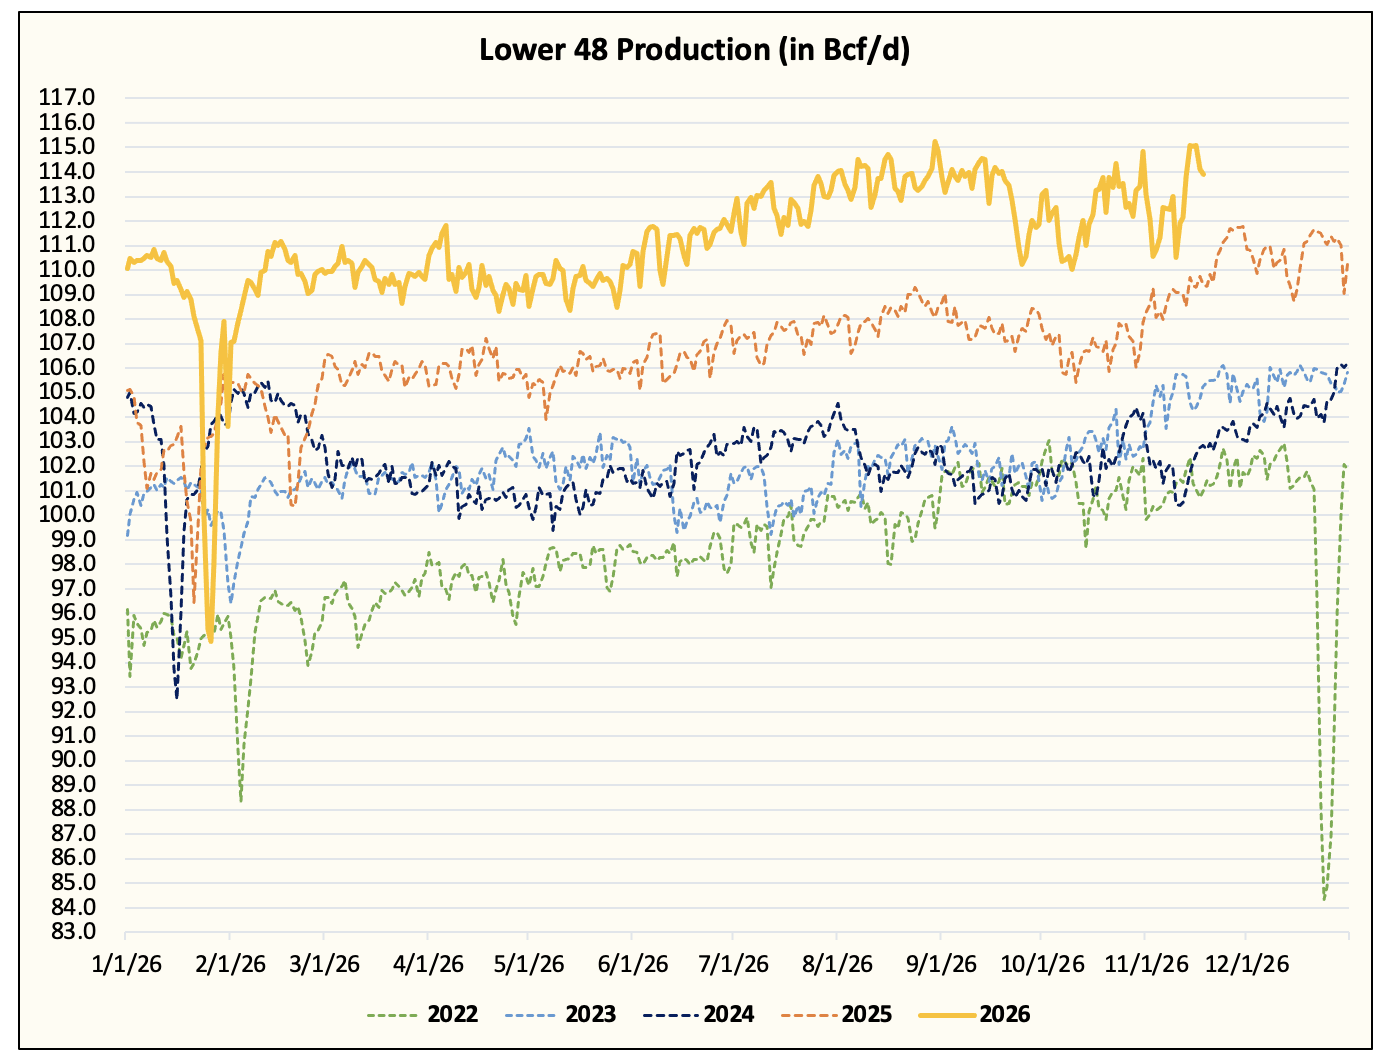
Lower 48 gas production remains far too high for demand balances in 2027. Lower 48 gas production reached ~115 Bcf/d, about 2 Bcf/d higher than our initial exit assumption. Natural gas demand has also been revised higher, so on a forward-looking basis, the market remains ~1.5 Bcf/d oversupplied.
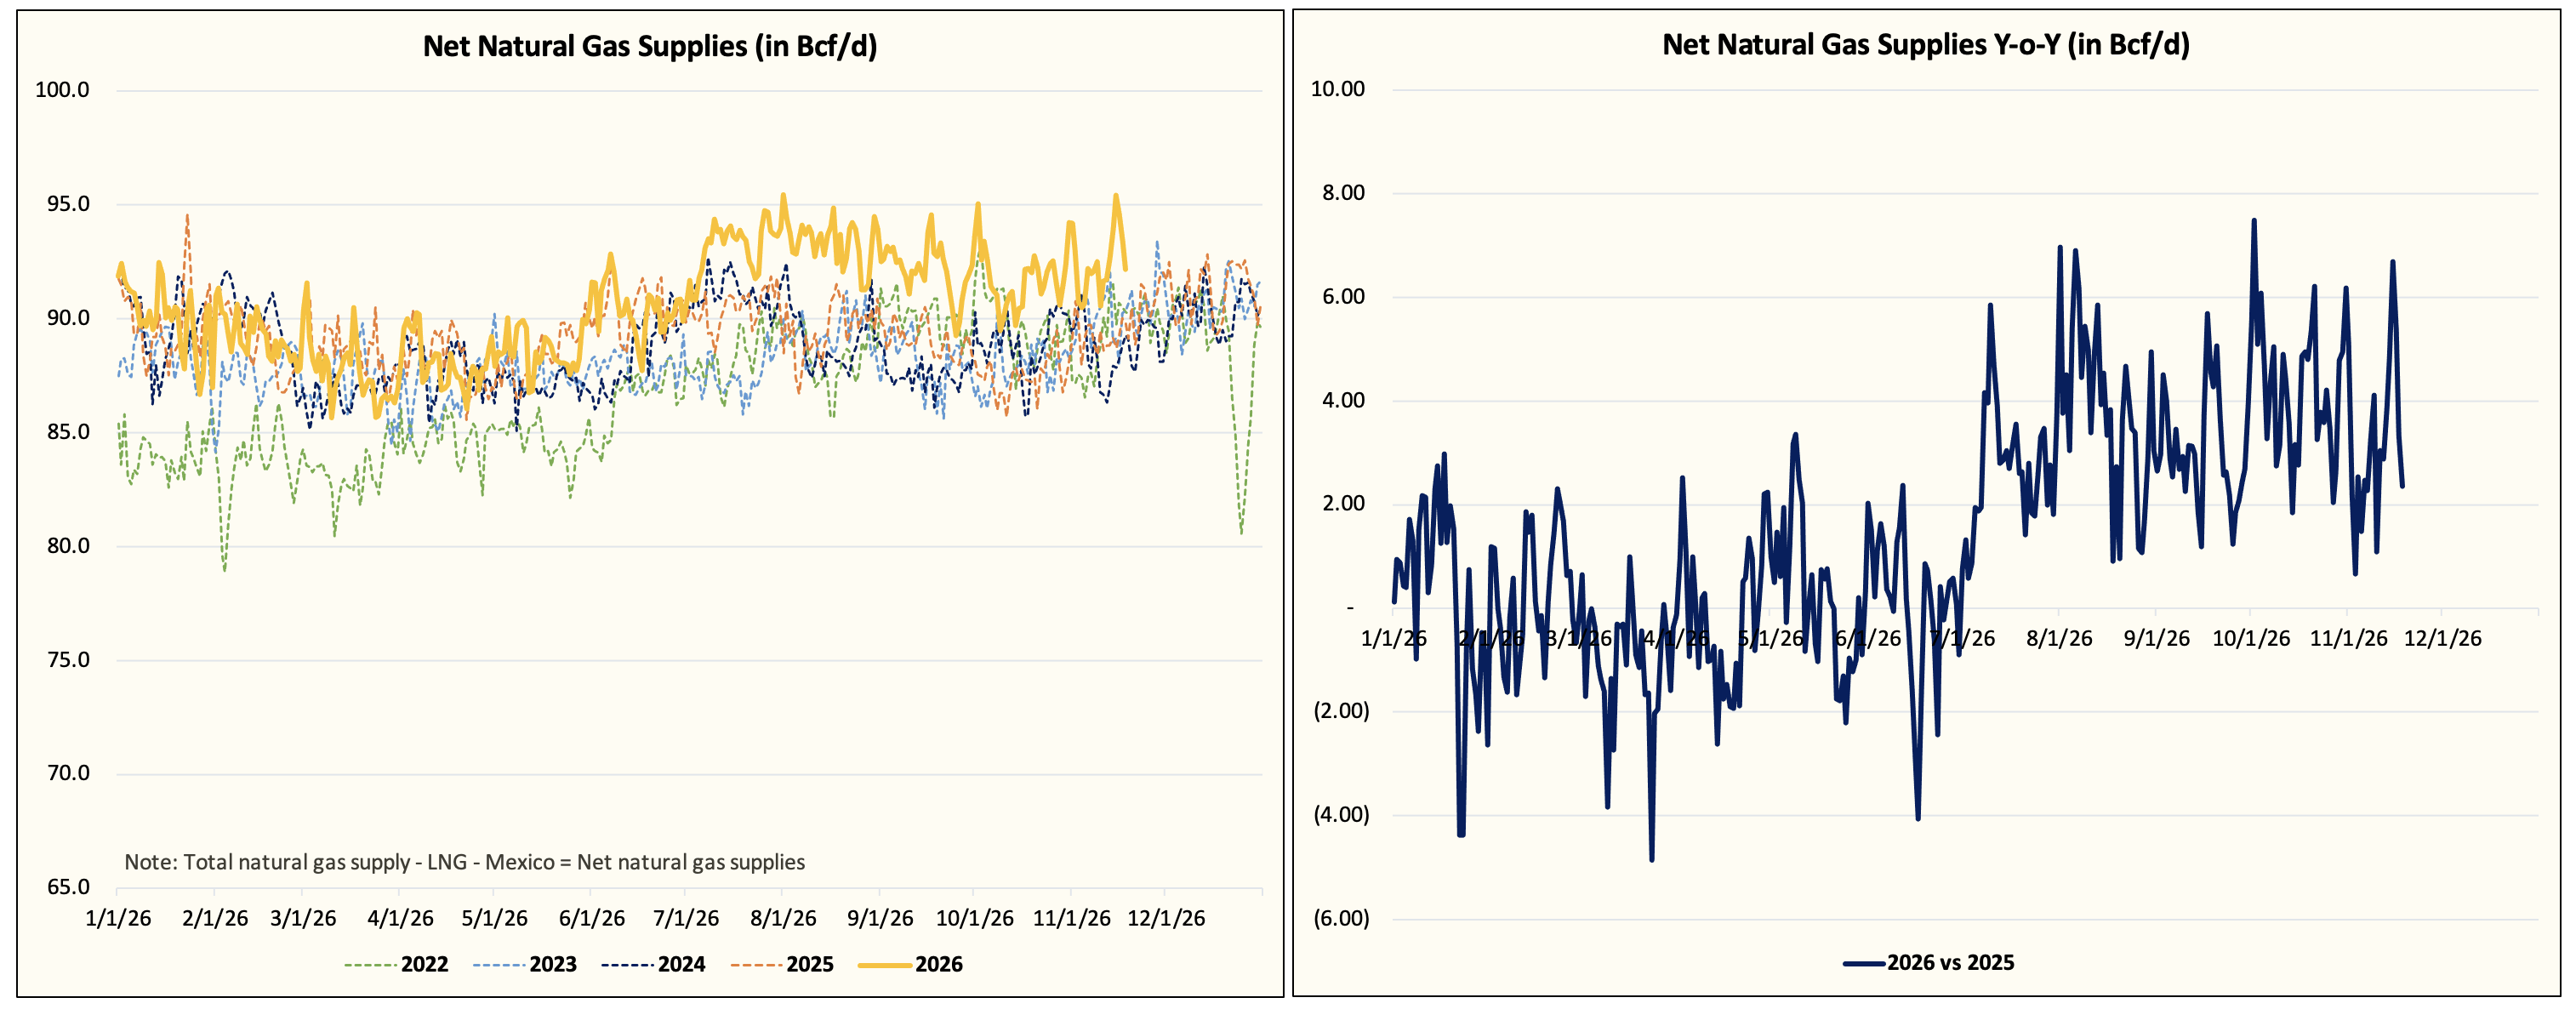
Net natural gas supplies (production growth - export demand growth) have averaged 3.5 Bcf/d higher y-o-y.
Power burn demand is ~2.1 Bcf/d higher y-o-y throughout the injection season, driven by warmer-than-normal weather and strong underlying demand growth.
Strong power burn demand in 2027 will be a key tailwind for natural gas, but without any immediate LNG or Mexico gas export demand, the injection season will be hard to get through.