

By: Jon Costello
Transocean (RIG) shares have been clobbered over the past few trading sessions, down 25.6% since October 30, versus the XLE’s 12.2% decline over the same period. I believe the selloff is partly due to macro angst toward oil and partly to weak headline third-quarter results, which the company reported on November 2. Overall, I think both are overblown and that the current share price represents a good entry point for investors willing to hold for at least three years.
Macro Oil Weakness
The general macro angst is the easy part to explain. Transocean shares are correlated with oil prices. The company’s large market cap for the energy sector and its relatively high leverage make it a favorite plaything of macro funds looking to short oil through means other than futures. Its short interest is pushing 30%.
The following table shows the tight correlation between Transocean shares and WTI. The relationship is peculiar, as the company’s results and prospects are not tied to spot crude prices. Clearly, they depend far less on spot oil prices than those of many other larger oil companies, such as E&Ps.
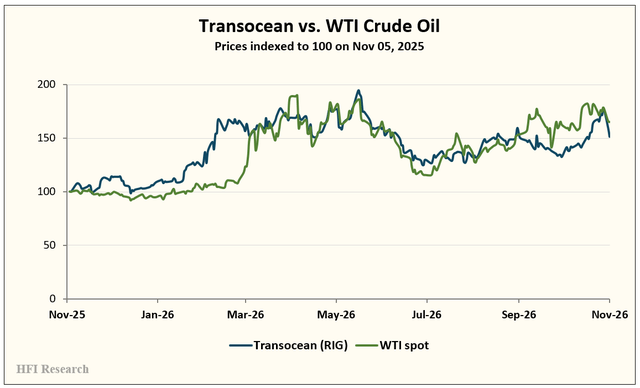
As Transocean’s leverage comes down after its Valaris (VAL) acquisition and continued efforts to pay down debt, while its earnings stabilize over the coming quarters, I expect macro funds will grow less fond of using the shares as a shorting instrument. If so, this should temper some of the volatility the shares have exhibited for many years. It might also reduce the tight correlation with oil. Periods of macro oil weakness like this one would be less likely to send the shares reeling.