

By: Wilson
I am a value investor by nature, but my investing experience has taught me to be more attuned to sentiment and price action. As Jon and I look at the broader investing landscape through the lens of energy specialists, I don’t see how any of this will end well.
Jon published a WOMM piece yesterday saying he doesn’t see any bargains in the market. It’s a public article, and it’s worth 6-7 minutes of your time to read it. In general, we are on the same page, and while Jon is more conservative and leans towards doing “nothing,” I am a bit more adventurous (and stupid), as I put on a small short position on ARKK.
You see, from the lens of an energy specialist, what we are seeing in the oil market today is just the tip of the iceberg. The Strait of Hormuz issue will be an ongoing conflict, and the market still sees it as transitory.
Why? How could that be?
It’s pretty simple really. Most people are too lazy to do the work. No, I really mean it. They look at the price action and conclude that nothing meaningful is going on.
S&P 500 near an all-time high? Yeah, it’s probably a nothingburger.
Nvidia guidance shows stellar AI demand growth? Yeah, it’s probably a nothingburger.
Over the past decade, energy has been the sector where you throw your career away. For those of us who survived, the numerous battle scars can fill a bookshelf. I can’t count how many times I thought about quitting. You can read through the archive in the “memo” tab to get a glimpse of the pain we all had to go through.
But now that energy is front and center in the global investing landscape, most people are still choosing to ignore it because it’s transitory. IEA, the energy agency created to help the world avoid an oil shortage, continues to blatantly publish reports that sound like propaganda pieces.
“We will be fine,” it says.
Source: IEA
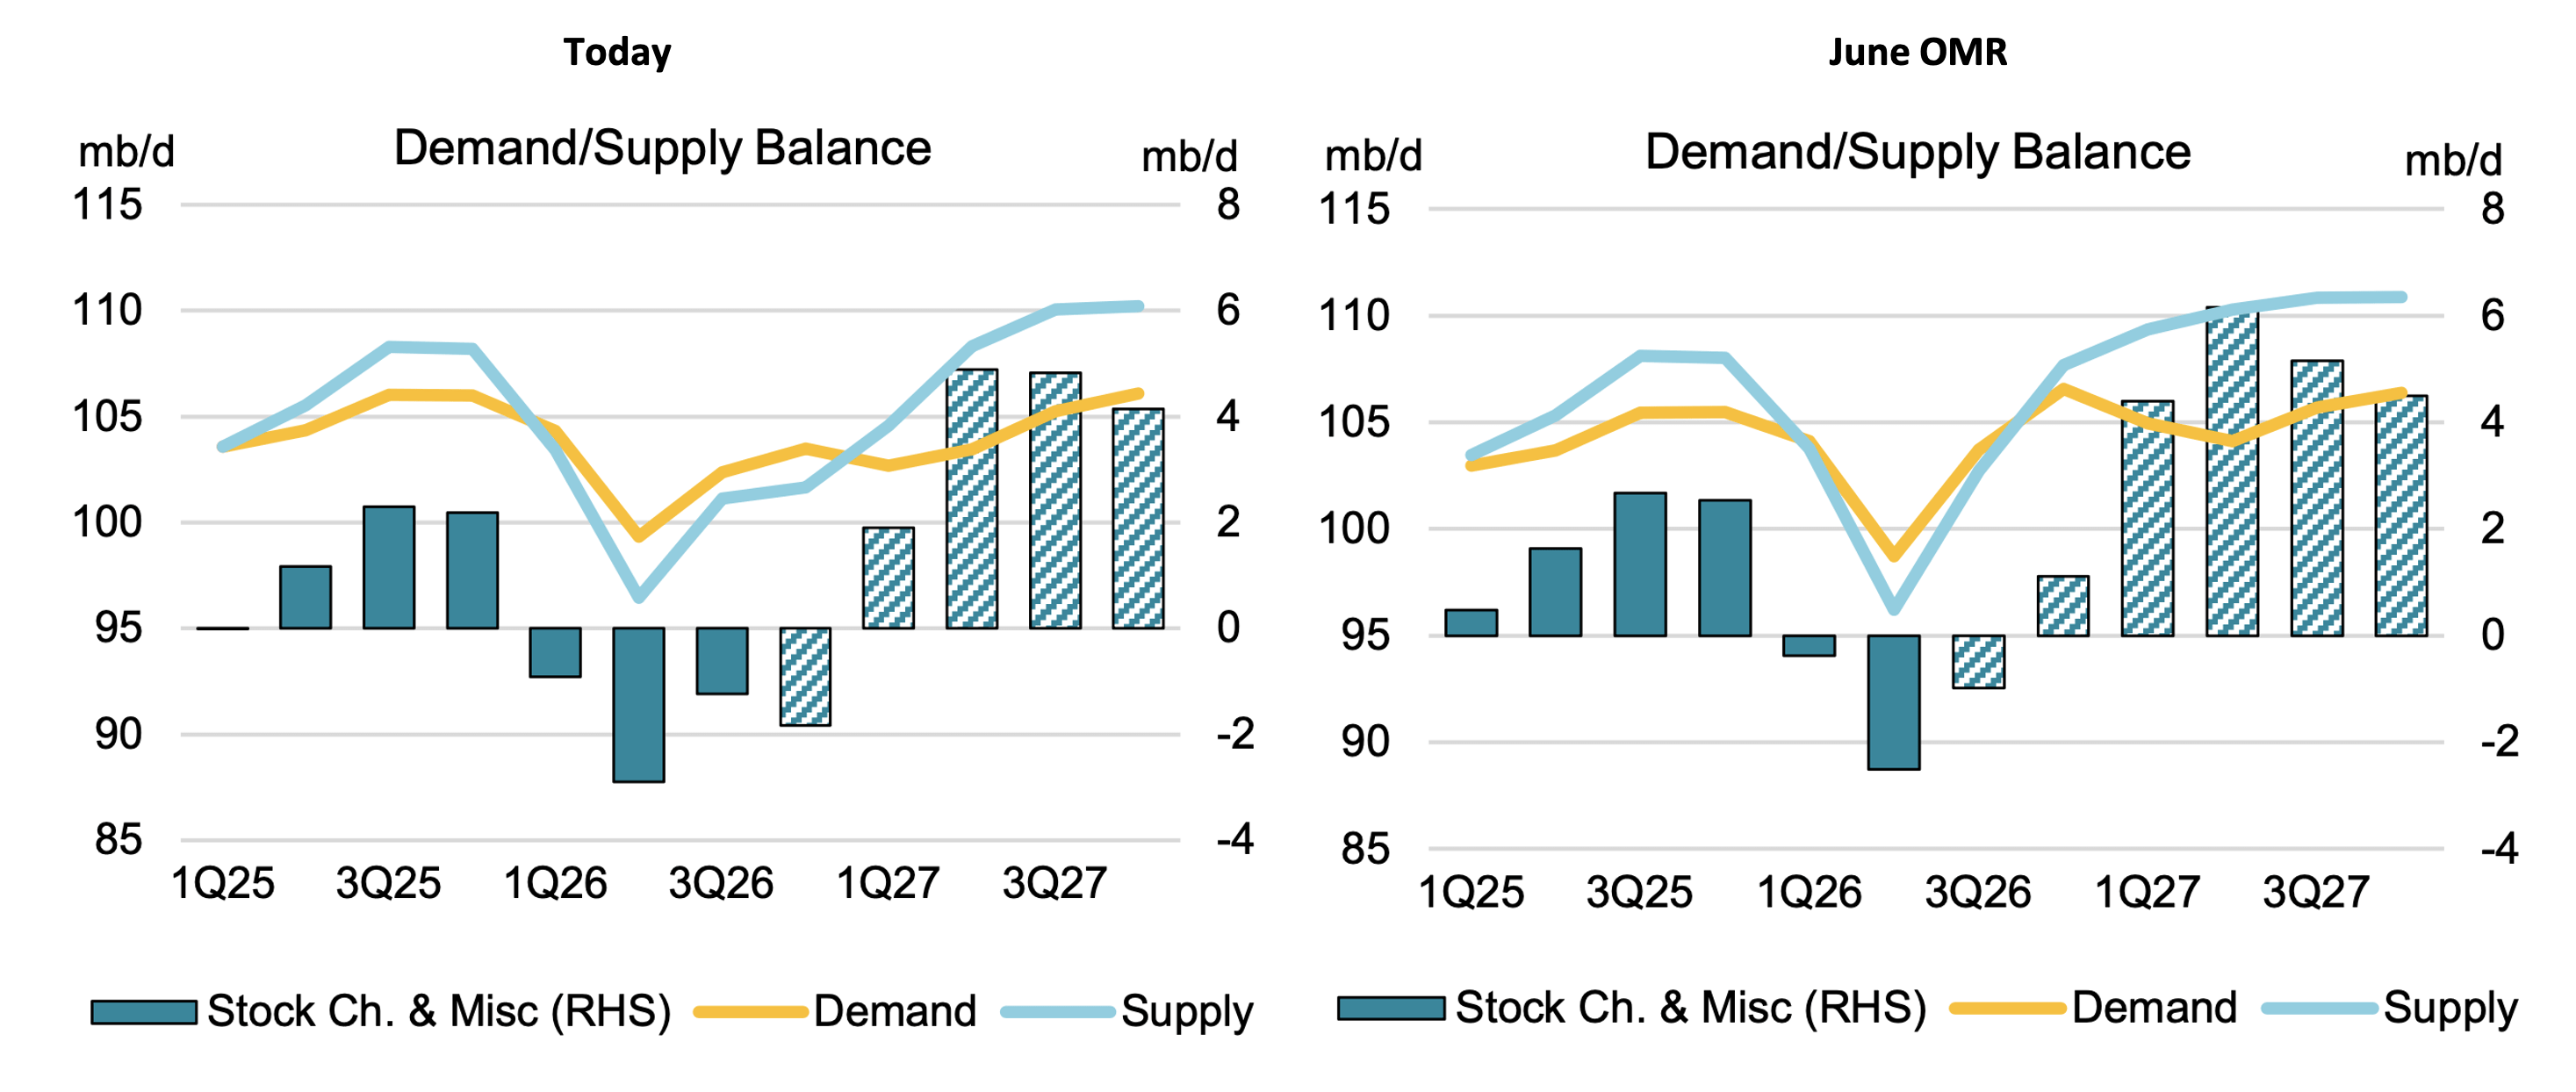
All you have to do is compare its forward oil deficit projections today with what it published in June. Another quarter went by; it revised the deficits higher, changed the Q4 2026 surplus into a deficit, and then continued to forecast a 2027 surplus.
Seriously, that’s not analysis. That’s Excel drag on steroids.
And although this kind of stuff gets on my nerves, as you can probably tell from the tone of this memo, it still gives me hope that the worst is ahead of us. It’s usually never a good thing when IEA panics, because when it does, it’s probably the time to sell everything.
But if my read on the market is right, the only way we reach the “fevered” sentiment point is for the broader market to sell off.