

By: Wilson
I’m not going to sugarcoat this; we are now in the worst of both worlds. One signal I gave myself after the midterm election blue tsunami was to watch Trump’s words for clues, and boy, it doesn’t look good.
The broader equity market finally sold off yesterday as people are attributing the material sell-off to liquidation. But instead of asking why we were there in the first place, first-level thinking never ceases to amaze me. The equity market should never have rallied after the Iran War started. Inflation was going to spike along with oil; we had an impending shortage and no resolution on the horizon, and tech stocks were trading over 30x earnings. You can’t reason with insanity, and this time was no different, but I digress; it’s not even about the equity market today.
The problem is incentives. Shortly after the midterms, I had the thesis that he would blame the Democrats for anything bad that happens to the economy, the stock market, or... you guessed it, the oil market.
And boy, Trump did not disappoint.

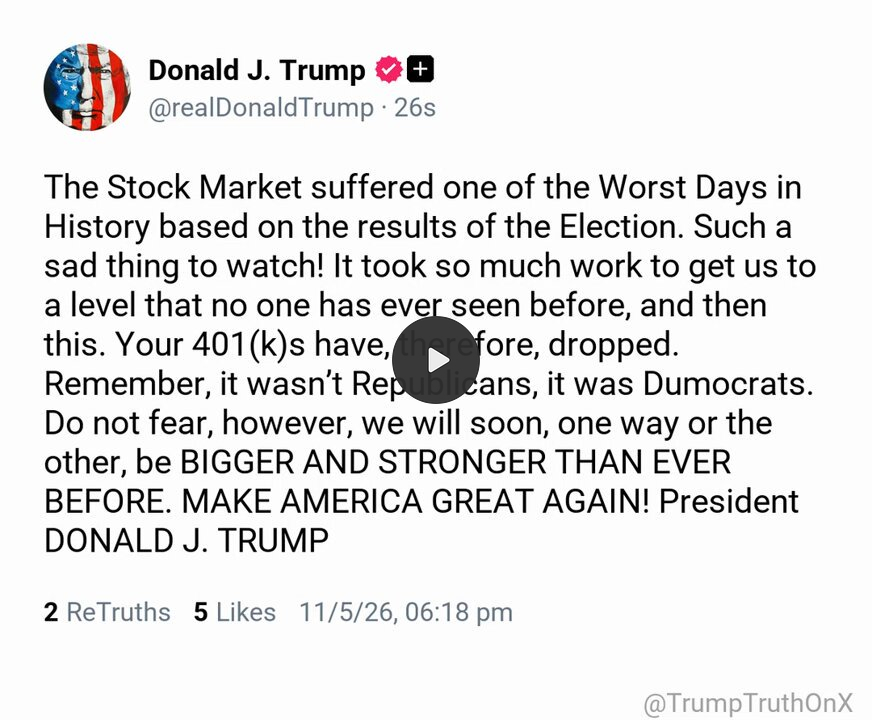
Soon after, he followed up with another one, and I quote, “You only have yourselves to blame!“
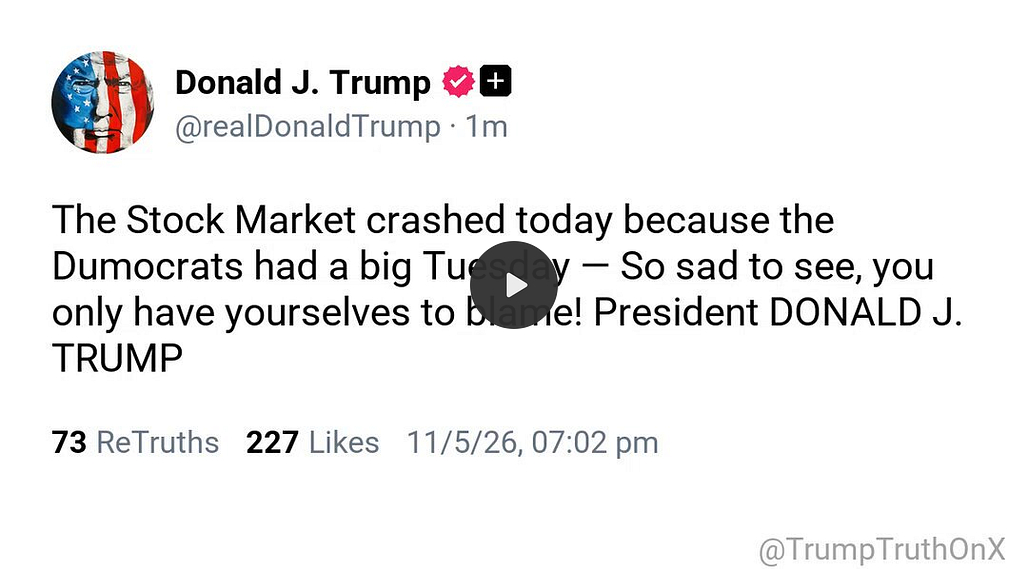
You see, the market continues to believe that President Trump is a hard man to read. I have a surprise for you, he’s not. The idea that Trump always chickens out isn’t the correct diagnosis because you have to think about incentives. He’s only TACOed because 1) he wanted to win the midterms and 2) he wanted to push stock prices up and oil prices down.
And that’s why the political messaging immediately after the midterms told you everything you need to know about incentives. He is now changing gear. If the stock market rallies, it makes him look bad, and if oil prices go down, it will be the Democrats.
I wrote on Monday in my WCTW piece that it’s all about incentives. Trump could still choose to not attack Iran, but the idea that he will come to a quick peace deal is just lazy thinking.
Why?
Because we are now in the worst of both worlds.