

The oil buffers are gone.
Excluding China, global onshore product inventories are sitting at operational minimums. Refineries cannot even go into maintenance right now because if they did, we would be looking at immediate localized shortages.
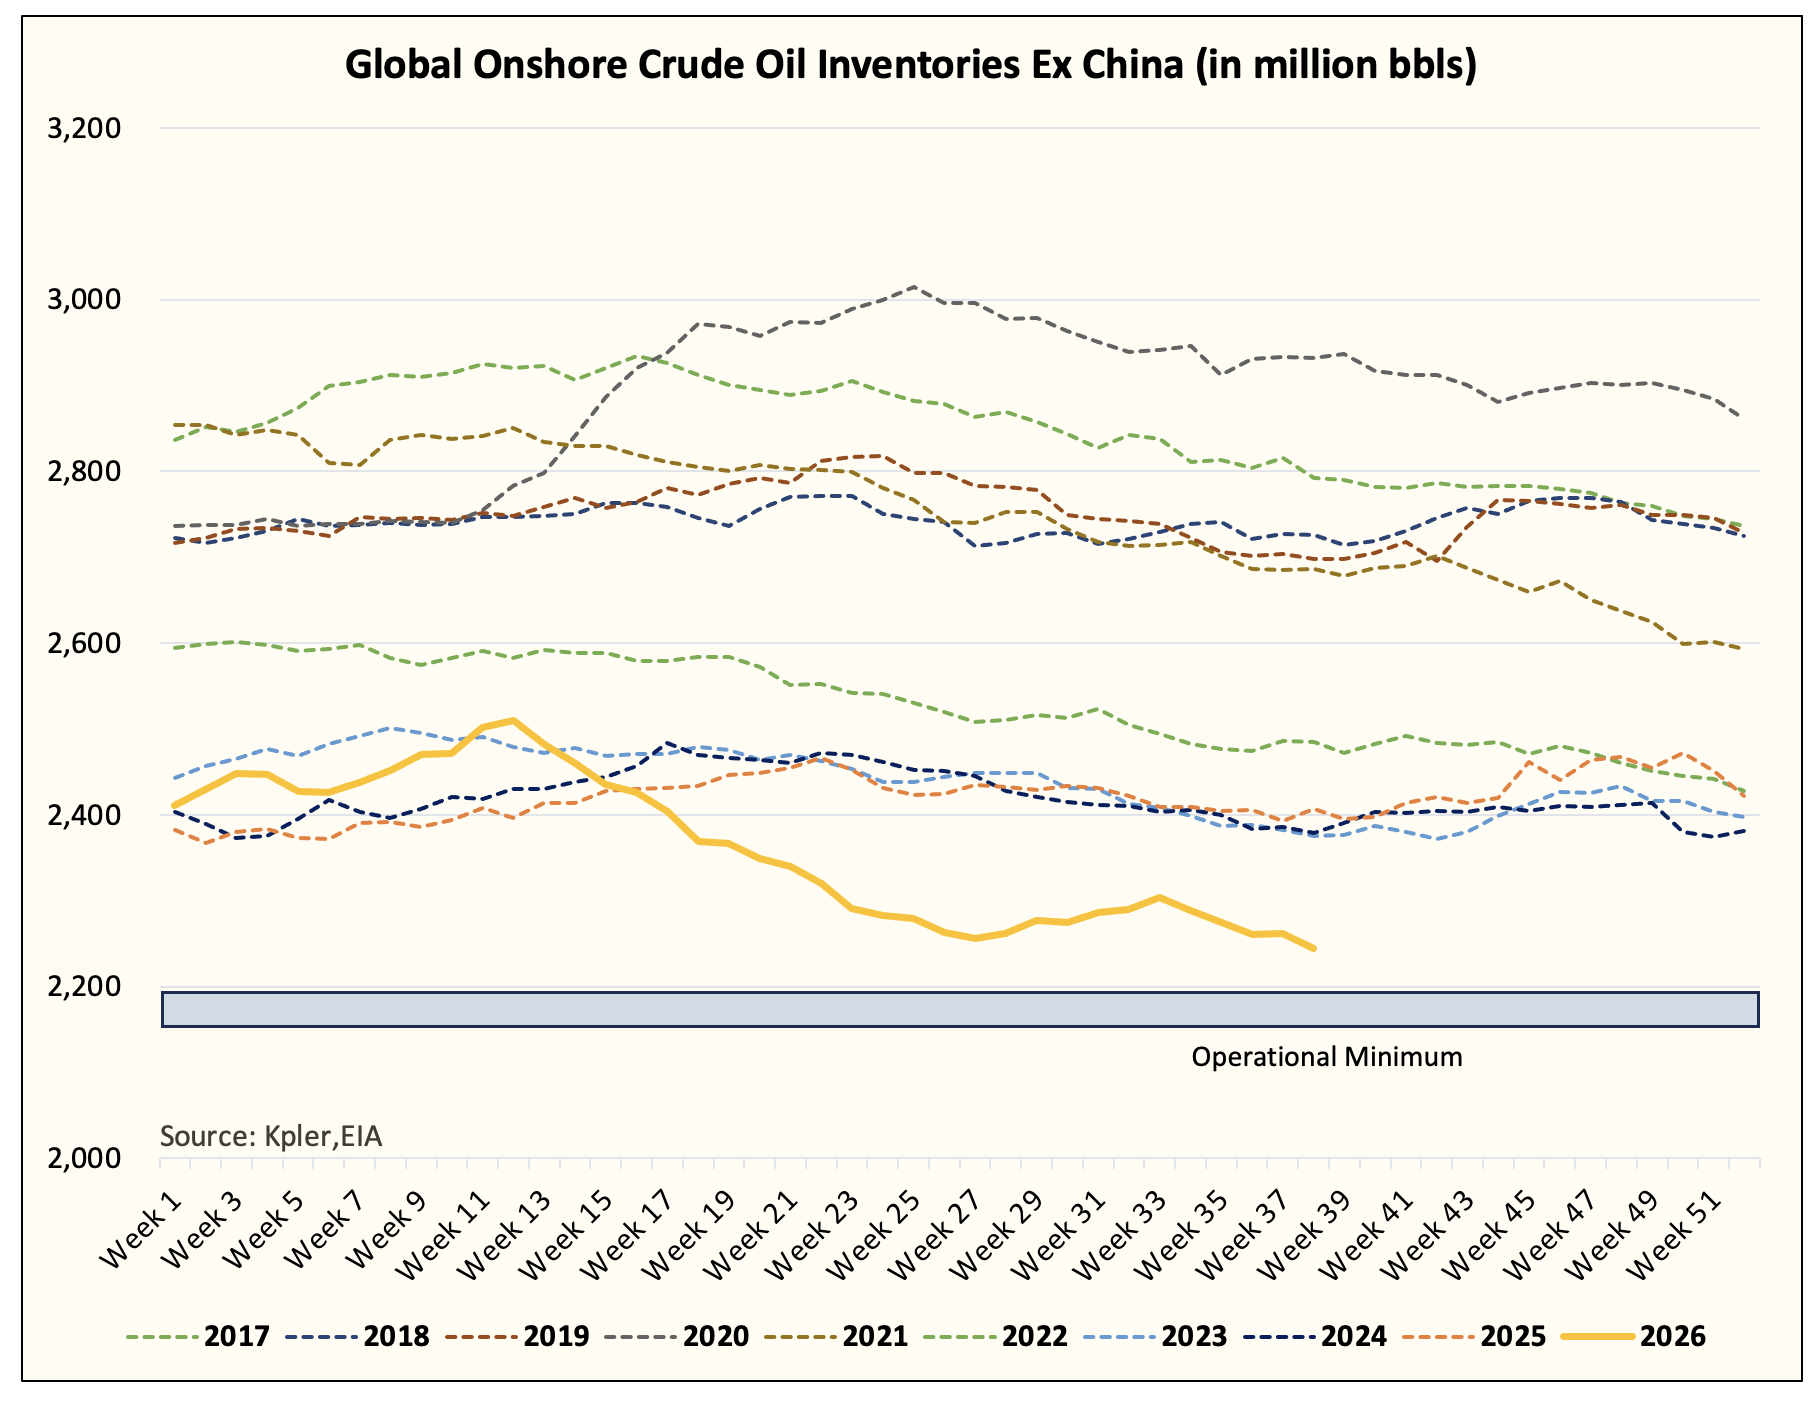
For the crude oil segment, we are literally spitting distance away from reaching operational minimums. If we look at this category excluding the US, the picture shows another 8-10 weeks.
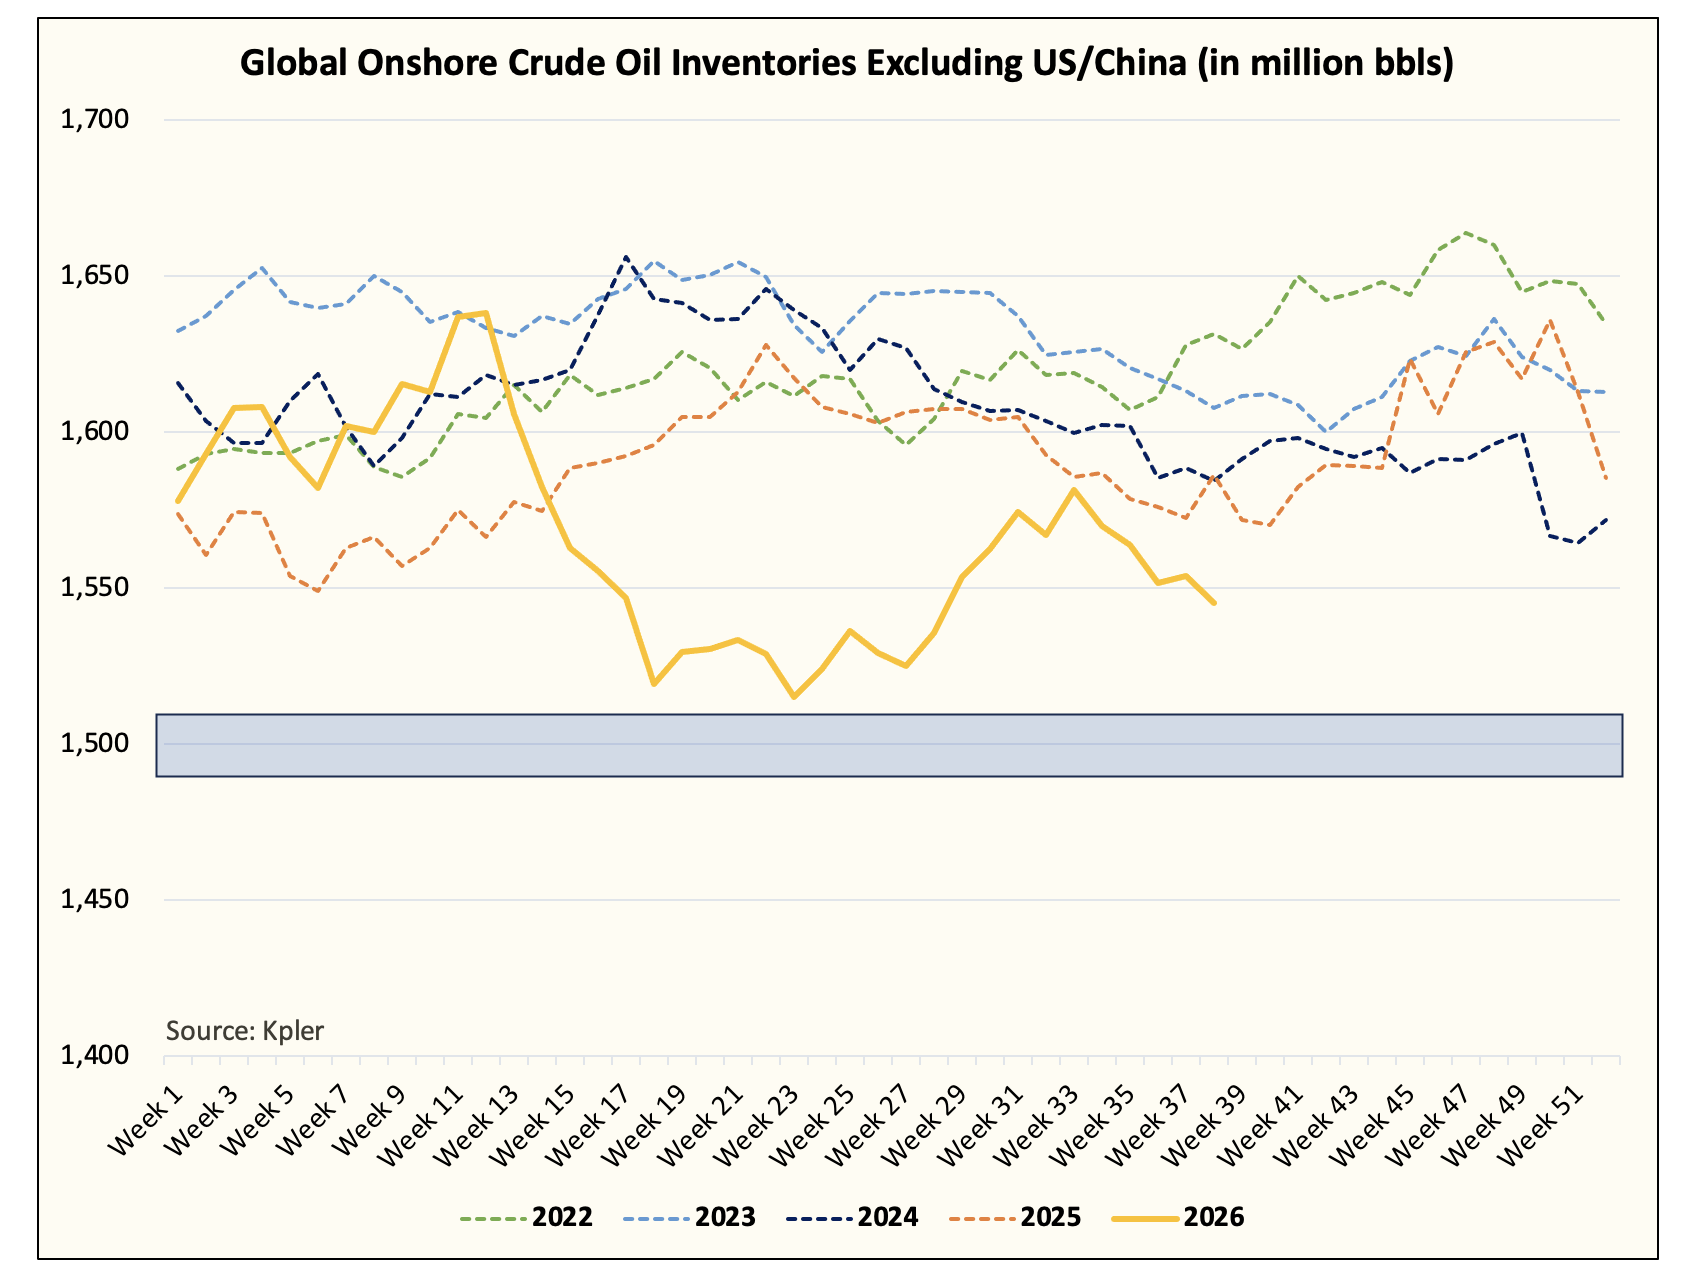
The buffer isn’t as high as everyone thinks. In reality, most crude oil in storage is for operational purposes. For global onshore ex-US and China, we’ve already tested the operational minimums back in April.
What’s particularly scary about the data we are seeing is that the moment China started buying crude, the pressure on everyone else showed up in storage data.
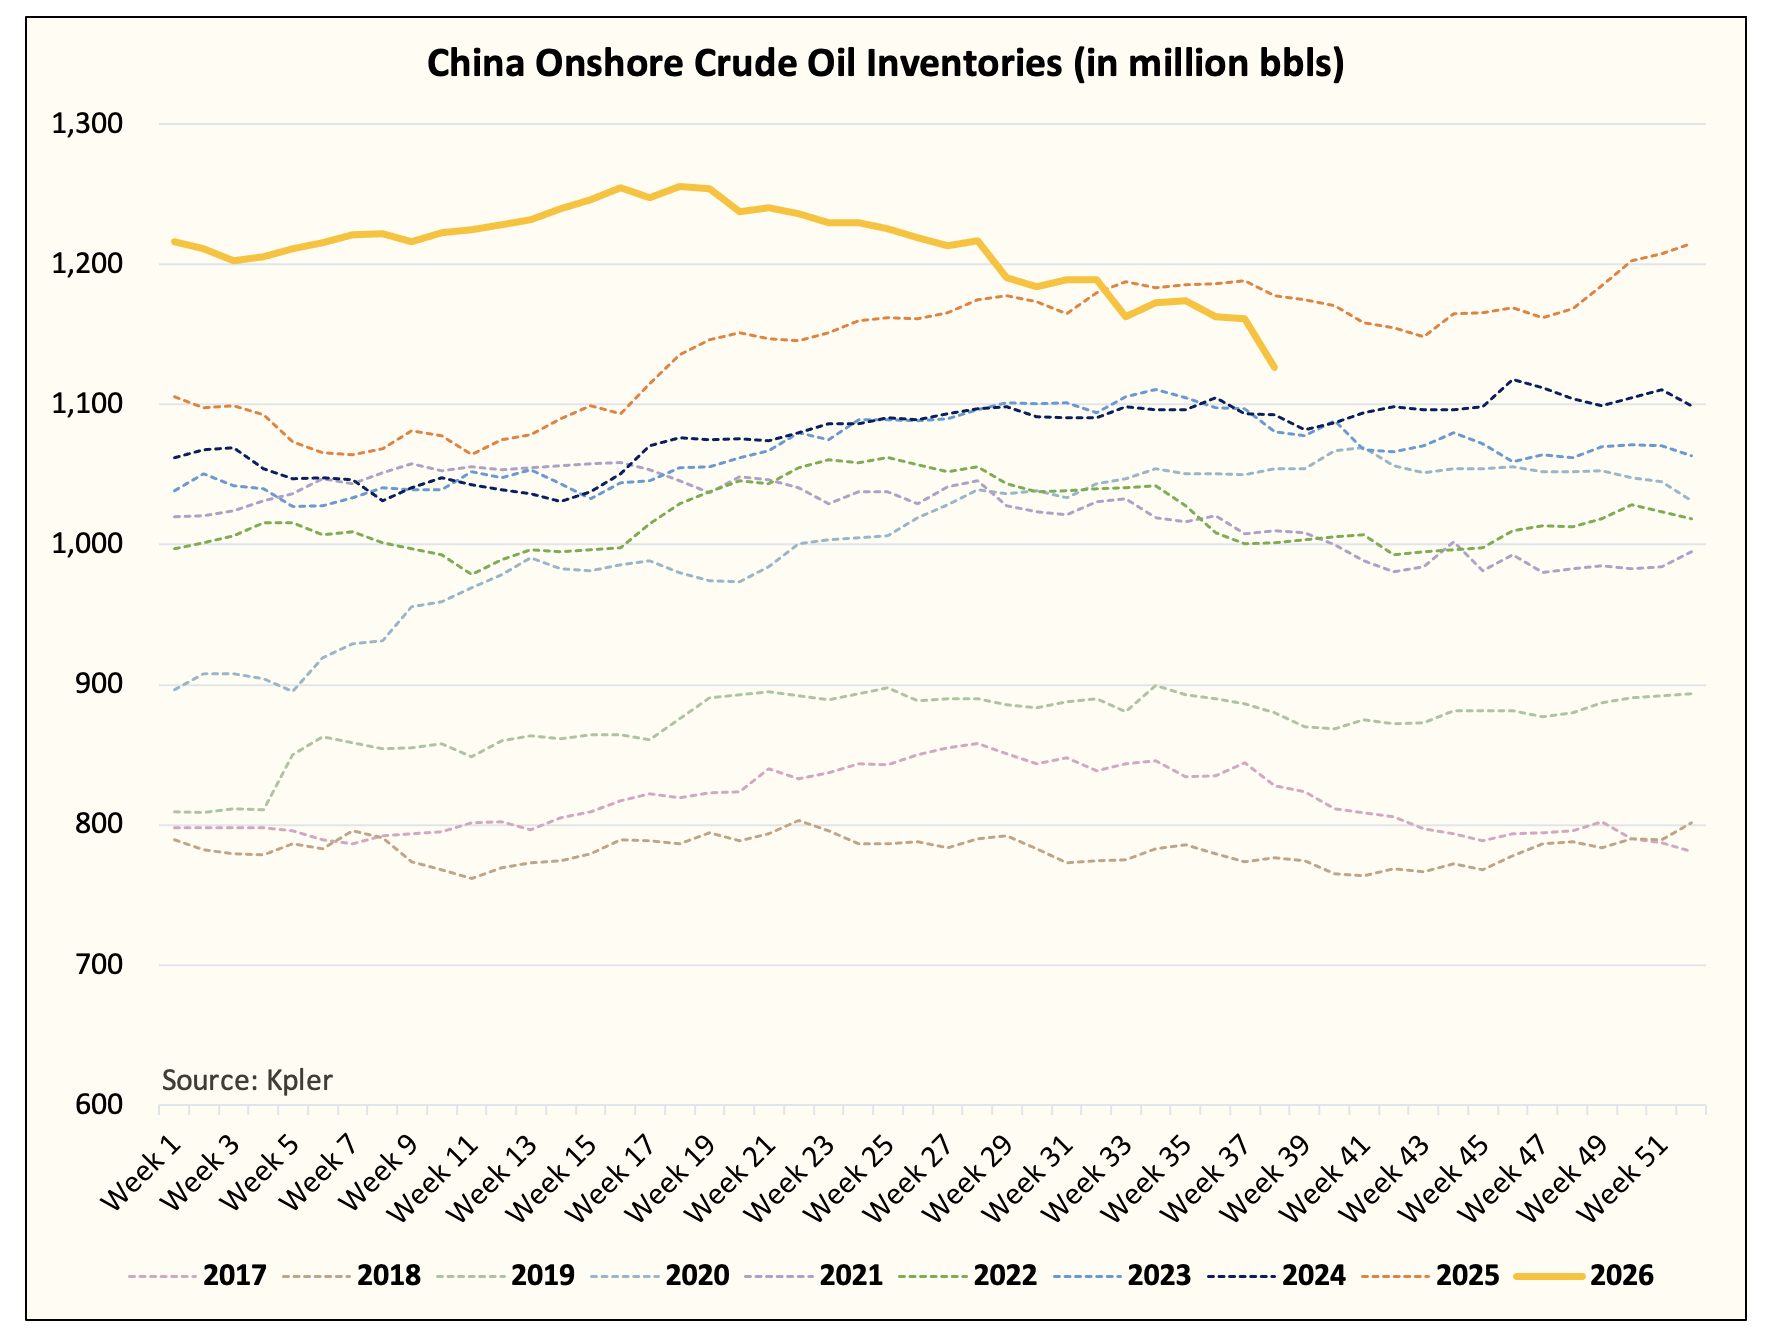
Yet, despite all the Chinese crude buying, satellite onshore storage providers show declining inventory... Surprised?
No, and I was perhaps the only one who was saying this at the start of the conflict, but China’s onshore crude inventory data is a black box. No one really knows what’s going on, so imports climbing while storage falls just shows the data was bad to begin with.
I guess the rest of the world is just finding out about this the hard way. As I wrote in my endgame piece, I’m usually early when it comes to things like this.
Now that we are here, what does all of this mean for the oil market and the oil trade?